Yes. Property tax in Egypt is real, it is collected, and it was rewritten this year. Built property is taxed at 10 per cent of its net annual rental value under Law 196 of 2008, amended by Law 3 of 2026 and published in the Official Gazette on 2 April 2026.
The amendment raised the exemption, and that is the part being misreported. The threshold moved from EGP 24,000 of net annual rental value to EGP 100,000, which the Real Estate Tax Authority equates to about EGP 8 million of market value, up from about EGP 2 million. The old figure is still on the Authority’s own Arabic FAQ page and appeared in Egyptian press on 3 October 2026.
The exemption covers one unit: your primary residence. A chalet on the North Coast or an apartment on the Red Sea is not that unit, and carries no shelter at all.
Where to invest in Egyptian property
Does Egypt Have a Property Tax? There Are Three
Three taxes touch a property in Egypt. Two of them were rewritten in 2026. Confusing them is the most common error in this subject.
| Tax | Rate | Charged on | Governing law |
| Annual property tax | 10% | Net annual rental value assessed by committee, not market value | Law 196/2008, amended Law 3/2026, Gazette 2 Apr 2026 |
| Disposal tax on selling | 2.5% | Gross disposal value with no deduction of cost | Law 91/2005, amended Law 151/2026, Gazette 28 Jul 2026 |
| Income tax on rent | Progressive, to 27.5% | Half of gross rent, after a 50% statutory allowance | Law 91/2005 |
The 2.5 per cent is not a capital gains tax. It is charged on the whole sale price with no deduction for what you paid, so it applies whether you made a profit or a loss. Selling a residential unit carries no VAT: exemption item 28 of VAT Law 67 of 2016 covers “renting and selling vacant land, agricultural land, buildings, housing and non-housing units,” which includes a new unit from a developer.
What Did Law 3 of 2026 Change?
| Item | Before | After Law 3 of 2026 |
| Primary residence exemption | EGP 24,000 net annual rental value, set 2014 | EGP 100,000 net annual rental value |
| Authority’s stated value equivalent | About EGP 2 million | About EGP 8 million |
| Discount for filing on time | None | 25% residential, 10% non-residential |
| Late-payment charges | Uncapped | Capped at the tax itself |
| Backdated tax on unsurveyed units | Payable | Waived entirely if the owner comes forward |
| Pending disputes | Litigated | Settle at 70% of the disputed amount |
| Filing and payment | In person | Electronic, one declaration for units in several directorates |
The 10 per cent rate did not change, and neither did the deductions: 30 per cent of gross rental value for residential units and 32 per cent for non-residential, taken as a maintenance allowance before the tax applies.
One caution we are leaving open rather than guessing at. Sources disagree on whether the EGP 100,000 is applied before or after that 30 per cent deduction. Ahram Business reads it one way, a worked example in Al-Watan the other. On a borderline unit the difference decides whether you pay, so ask your accountant rather than trusting published arithmetic, ours included.
Is My North Coast or Red Sea Unit Taxed?
Yes, at 10 per cent of net annual rental value, from the first pound. Article 18 exempts the unit the taxpayer uses as a primary residence for self, spouse and minor children. One unit. Every other unit is taxable, and a resort chalet is by definition not the primary residence.
There is no separate threshold for second homes, no vacancy relief and no resort concession. Marsad Omran, which tracks Egyptian built-environment policy, notes the amendments added no mechanism to tax vacant holiday property more heavily either. Second homes sit on the same 10 per cent as everything else, without the shelter.
The change that matters most to a coastal owner is not the rate. It is Article 14. Law 3 of 2026 obliges the managements of tourist villages, integrated urban communities, hotel facilities and housing associations to file a statement with the Real Estate Tax Authority naming the owners and users of every unit, with national ID numbers, addresses and unit specifications.
Read that plainly. The compound management now hands the tax authority a list of who owns what. For a market where much coastal stock was never on the tax rolls, that is the mechanism by which it goes on them. The Senate changed the wording during drafting, replacing “tourist resorts” with “tourist villages” and adding “integrated residential communities”, but the duty survived.
And the tax follows the unit, not the passport. Law 196 of 2008 taxes built property by reference to the property and its rental value; nationality does not appear in the exemption, which turns only on whether the unit is your primary residence. You will find pages claiming foreigners pay no annual property tax in Egypt. That does not sit with the structure of the law, and we flag it rather than repeat it. On ownership, Law 230 of 1996 allows a non-Egyptian up to two properties, each no larger than 4,000 square metres, for residential use.
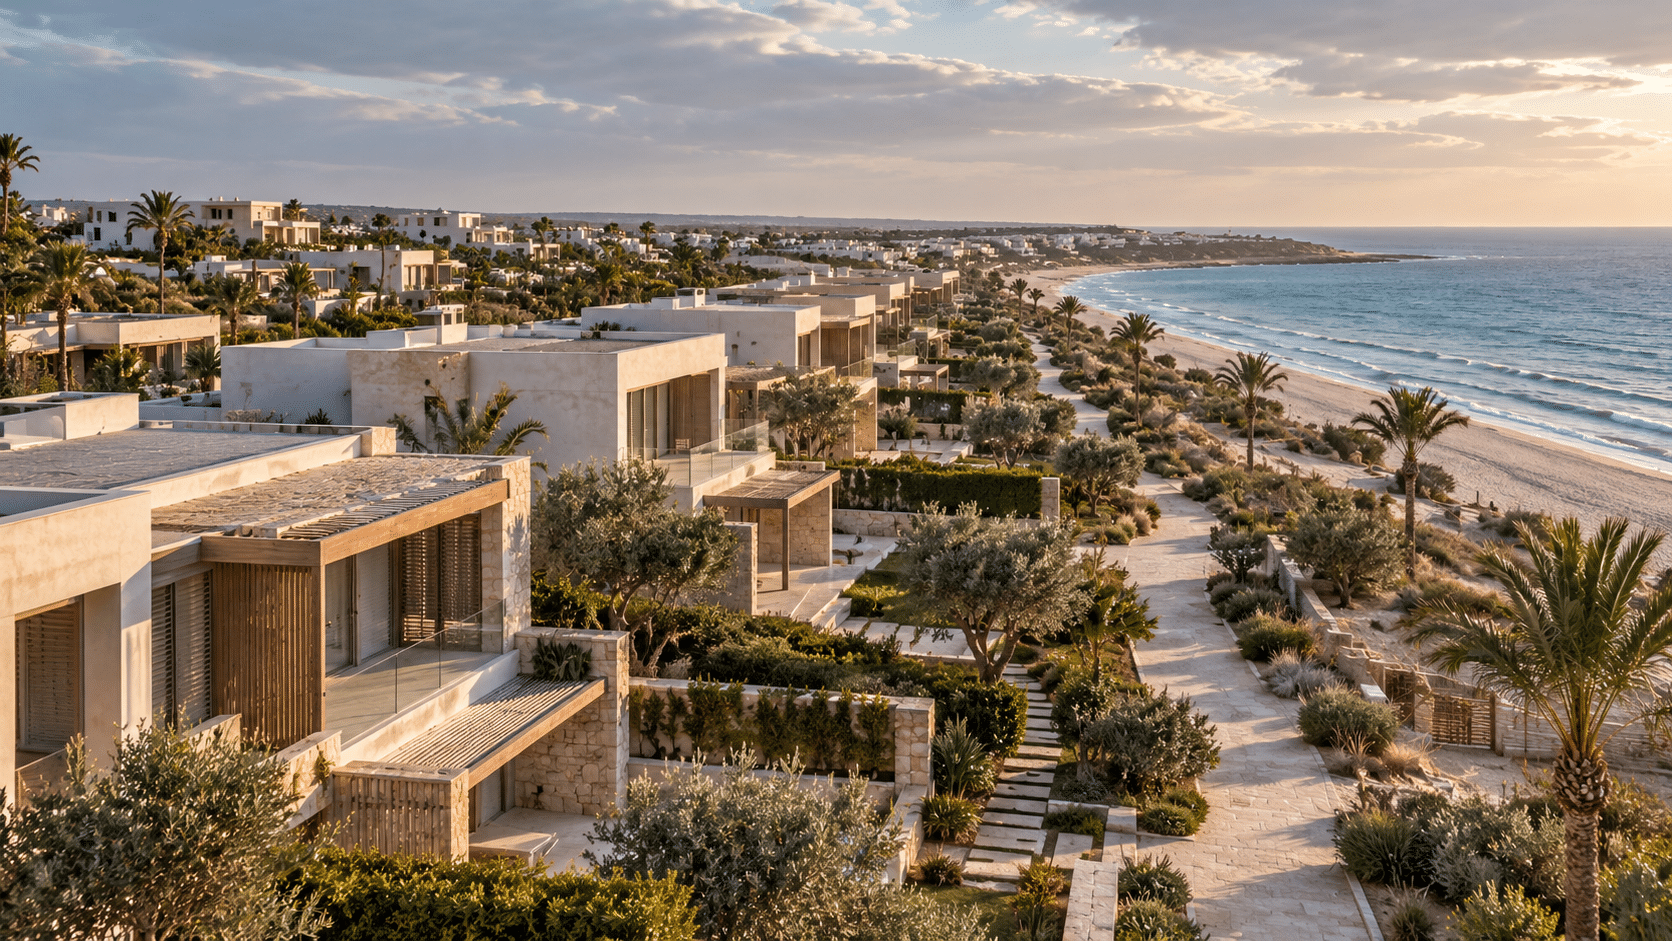
Ras El Hekma, where much of this stock is being built
Why Egypt is on the international property map
What Do I Pay When I Sell?
2.5 per cent of the sale price, with no reduction and no deduction of what you paid. The seller pays, within 60 days of the disposal, extended from 30 days by Law 151 of 2026. It covers built property and land prepared for building, and catches sales, gifts, wills and usufruct rights beyond 50 years.
Law 151 of 2026 also fixed the taxable value at the figure in the contract and put the burden of proving a different one on the Egyptian Tax Authority. And it confirmed that selling property does not by itself make you a professional trader, however often you do it, which keeps the charge at 2.5 per cent rather than business profit rates.
Inheritance changed in July 2026 and the position is contested. Two Egyptian law firms and two tax services read Law 151 of 2026 as expressly taxing an heir’s disposal of inherited property, sold as it stands or after building on it. Older pages still say heirs are exempt. If you are selling something you inherited, put that to a lawyer before anything else.
The reliefs we can see surviving:
- Contribution of property to a joint-stock company, if the shares are held five years
- Gifts to a spouse, ascendants and descendants
- Gifts to government, local administrative units and public-benefit bodies
- Forced administrative or judicial sales, and expropriation for public utility
There is no primary-residence relief and no one-off-sale relief.
What Are the 2026 and 2027 Deadlines?
| What | When | Why it matters |
| Declaration for 2026 | End of December 2026 | Extended from 30 September by the Finance Minister. Filing earns the 25% discount |
| First instalment | End of June | Tax accrues 1 January and is paid in two equal instalments |
| Second instalment | End of December | Or pay the whole year at the first date |
| Dispute settlement at 70% | To 2 April 2027 | Settle a pending dispute at 70% of the amount in question |
| First tax on newly declared units | 2027 | Exemption status is determined in the 2027 valuation phase |
Filing is not the same as paying. The threshold exempts the tax, not the declaration, and the head of the Authority has been explicit that every unit must be declared so its status can be determined. Valuations run in five-year cycles, and Law 3 of 2026 now obliges the Authority to publish its indicative price map at least 90 days before valuation starts, which gives an owner something to object to before an assessment lands.
Is Property Tax in Egypt Enforced in Practice?
Collection is small and rising, and the state has stopped pretending otherwise. The Authority’s own figures put receipts at EGP 1.842 billion in 2021/22, 2.730 billion in 2023/24 and 3.166 billion in 2025/26, which it reported as breaking three billion for the first time. Set against total Egyptian tax revenue of EGP 2.2 trillion in 2024/25, that is a rounding error.
One caveat on that figure, because it is the only one we can source to the Authority itself. Other published numbers for Egyptian property tax run an order of magnitude higher, with Enterprise reporting EGP 29 billion expected against EGP 18 billion budgeted. Nobody has established what each figure covers, so we quote the Authority’s own and say plainly that it may not be measuring the same thing.
The head of the Authority says that of roughly 55 million properties nationwide, only about 2 million are liable to residential property tax after the amendments. In early October 2026 the Authority reported 2 million units registered and about 1.2 million declarations filed, against a target of more than 10 million by December 2026.
The amnesty is the tell. Backdated tax is being written off entirely on units that were never surveyed, whatever their construction date, if the owner now comes forward. A state does not waive years of tax on stock it was already collecting from. Marsad Omran finds the Authority collected an average of 77 per cent of its own targets across 2014/15 to 2024/25, with collections falling in several years despite rising nominal prices.
So: property tax in Egypt has been under-enforced, the state is fixing that with digital filing, owner lists from compound managements and a 10-million-unit target, and the window in which coastal property sat outside the system is closing.
Final Word
Property tax in Egypt stopped being a theoretical cost in April 2026. The rate did not move, but the exemption, the discounts, the amnesty and above all the duty on compound managements to hand over owner lists did. If you own one home you are better off than you were. If you own a second one on either coast, you are inside a system that now knows where it is. Contact D5 Realty and we will tell you which of these applies to your unit, and where the question needs an accountant rather than a broker.
D5 Realty is a real estate consultancy, not a tax or legal adviser. Every figure above is cited to its law number and Gazette date so you can take it to a professional and check it. Several points here are unsettled, including the order of the calculation, the treatment of inherited property, and whether a coastal development sits inside a city boundary for the disposal tax. Confirm your position with an Egyptian accountant before acting.
Red Sea investment opportunities
Egypt’s top real estate developers
Frequently Asked Questions
- Does Egypt have a property tax in 2026?
Yes. Built property is taxed at 10 per cent of net annual rental value under Law 196 of 2008, amended by Law 3 of 2026 and published in the Official Gazette on 2 April 2026. It is assessed on committee-estimated rental value rather than market value, and collected by the Real Estate Tax Authority.
- How much property tax do I pay on a second home in Egypt?
Ten per cent of net annual rental value, with no exemption. The EGP 100,000 threshold applies only to the unit you occupy as a primary residence. A North Coast chalet or Red Sea apartment is a second home and carries no shelter, however modest its value.
- What is the current property tax exemption in Egypt?
A net annual rental value below EGP 100,000 on your primary residence, raised from EGP 24,000 by Law 3 of 2026. The Real Estate Tax Authority states the equivalent market value as about EGP 8 million, up from about EGP 2 million. That equivalence is the Authority’s own, not a figure in the statute.
- What tax do I pay when I sell property in Egypt?
A 2.5 per cent disposal tax on the gross sale value with no deduction for what you paid. The seller pays within 60 days, extended from 30 days by Law 151 of 2026. There is no primary-residence relief. Selling a residential unit carries no VAT.
- Do I still have to file if my property is exempt?
Yes. The threshold exempts the tax, not the declaration. The Authority requires every unit to be declared so it can determine status. The 2026 deadline was extended from 30 September to the end of December 2026, and filing on time earns a 25 per cent discount on residential property.